Could Rent-to-Buy Unlock More Costa del Sol Property Sales?
International demand for a home on the Costa del Sol remains remarkably strong. Yet as property values have risen, some buyers are becoming more thoughtful about how and when they commit substantial capital to a second home in Spain.
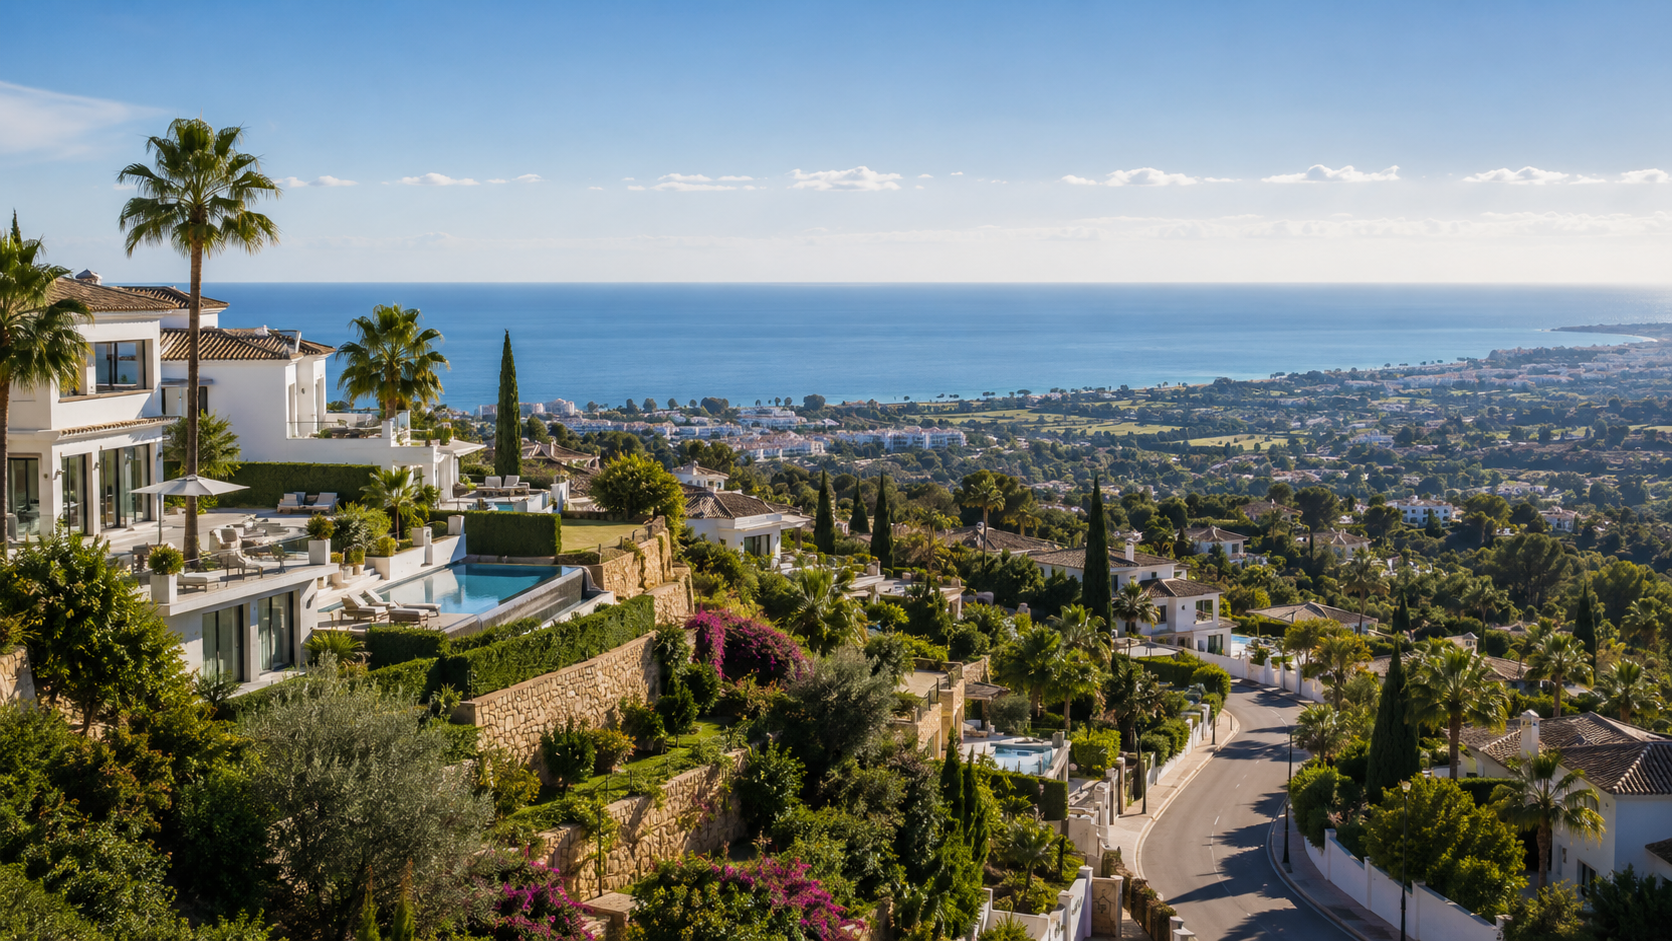
The Costa del Sol has lost none of its ability to attract people who dream of owning a home in southern Spain.
Buyers continue to arrive from across Europe and further afield, drawn by the climate, lifestyle, connectivity and the simple pleasure of having a place here to return to throughout the year.
Foreign purchasers remain an essential part of the Málaga property market too, accounting for around 37% of residential transactions across the province during the second quarter of 2026.
At the same time, something more nuanced is happening beneath those headline levels of demand.
In Marbella, 1,483 residential property transactions were recorded during the first five months of 2026. If that pace continued for the remainder of the year, the final figure would be around 3,559 transactions — below the 4,443 completed in 2025.
Prices, meanwhile, have risen strongly. The average price per square metre recorded in Marbella during the first five months of 2026 was almost 50% above its 2022 level.
That does not necessarily suggest a loss of confidence in the Costa del Sol.
Quite the opposite.
It may simply mean that after several years of strong price growth, buyers are paying more attention to the timing, structure and capital commitment involved in purchasing a second or third home.
For sellers, that raises an interesting possibility.
Rather than assuming that the only way to unlock a sale is to reduce the asking price, could there sometimes be value in changing the structure of the transaction instead?
The international buyer is still very much here
Overseas buyers are not a small corner of the Costa del Sol property market. In many of its most desirable locations, they are fundamental to it.
Across Málaga province, foreign purchasers represented around 37% of residential transactions during the second quarter of 2026. In areas such as Marbella, Benahavís and Estepona — particularly within the upper and luxury segments — international ownership is deeply woven into the character of the market.
Many of these buyers are not purchasing a principal home.
They may be looking for somewhere to spend the winter, a base for extended holidays, a future retirement property or simply another home from which to divide their time between several countries.
That makes their buying decision rather different from somebody who needs to find a permanent home for their family.
For many international buyers, the question is not:
“Can I afford this property?”
It may be:
“Is this the right moment to commit this much capital to a second home?”
That distinction has become more important as values have risen.
A buyer may remain entirely confident in the long-term appeal of the Costa del Sol while still wanting more flexibility over when they release several hundred thousand euros of capital.
A €750,000 second home requires a larger capital commitment
Consider somebody looking at a €750,000 apartment or townhouse.
They may have an excellent income, a valuable home in their own country and a healthy investment portfolio.
On paper, they are an excellent buyer.
But being able to afford something and wanting to release the capital for it immediately are not always the same thing.
Financing for a second residence or for a non-resident buyer can also be more restrictive than a mortgage on a principal home. Depending on the buyer and lender, somebody purchasing at €750,000 may need to provide around 30% of the property value themselves, sometimes more, before taxes and acquisition costs are taken into account.
The amount of readily available capital required can therefore move towards €300,000 surprisingly quickly.
At €1 million, the commitment becomes larger again.
For some buyers, that money may currently be invested elsewhere. Another property may need to be sold first. A business sale, investment maturity, inheritance or retirement may be expected within the next few years.
Others may already know that they want to spend more time in Spain but have not yet reached the point at which they want to restructure their finances around that decision.
This is less about hesitation over the destination and more about capital planning.
The second-home mortgage market shows the same gap
There are some interesting signs of this within the second-home mortgage market.
In July 2026, second homes represented 8.1% of mortgage applications handled through Idealista’s mortgage service, yet only 2.2% of completed mortgage operations.
That does not necessarily suggest a lack of buyers.
Second-home mortgages can simply be less attractive to lenders. They may involve smaller loans, shorter terms or borrowers who repay earlier than someone financing their principal residence.
For a market as dependent upon lifestyle and second-home purchasing as the Costa del Sol, that matters.
A buyer can be financially secure, genuinely interested in a property and still find that the traditional route from viewing to completion is not quite as straightforward as expected.
That is very different from saying the demand has disappeared.
Second-home buyers also have more to consider
Today’s international purchaser has more to think about than the property itself.
Spain ended its property-linked Golden Visa programme in April 2025, removing one additional incentive that had previously applied to certain non-EU purchasers investing €500,000 or more.
There has also been considerable political discussion around foreign property ownership, taxation and housing availability.
At the same time, regulations surrounding tourist accommodation have become more demanding.
For somebody considering renting their Costa del Sol home during periods when they are abroad, community rules, licensing and the wider regulatory framework can make a meaningful difference to the way they assess the purchase.
None of these factors has stopped international buyers coming to the Costa del Sol.
The numbers clearly show that they continue to buy.
But purchasing a second or third home is, by its nature, discretionary. The more elements involved in the decision, the more likely buyers are to think carefully about the timing.
That creates an opportunity for sellers who are able to offer flexibility.
What if the problem is not actually the asking price?
When a property has been on the market for longer than expected, the usual conversation eventually turns towards price.
Sometimes that is exactly where the conversation should go. A property that is materially overpriced will usually need adjusting if the owner genuinely wants to sell.
But there are other situations where the price itself may not be the problem.
Imagine an attractive apartment offered at €800,000.
Buyers view it. They like the location, the terrace and the community. Comparable homes support the valuation.
Yet nobody quite takes the final step.
The obvious response might be to reduce the property to €750,000.
But what if a prospective purchaser is not particularly concerned about paying €800,000 rather than €750,000?
What if their real hesitation is having to release €300,000 or more of capital today?
In that situation, a price reduction may solve the wrong problem.
Another way to look at the sale
Instead of immediately reducing the value of the property, the owner could potentially change when the buyer needs to provide all of the capital.
This is where a carefully structured rent-to-buy or deferred-purchase arrangement starts to become interesting.
How could rent-to-buy work on the Costa del Sol?
Rent-to-buy arrangements in Spain can be structured in different ways, and there is no single model that will suit every seller or buyer.
Broadly, the prospective purchaser rents the property while also receiving an agreed option to buy it within a defined period.
The future purchase price can be agreed in advance. There may be an initial payment for securing the option, while some — or potentially all — of the monthly rent can be credited towards the eventual purchase if the parties agree.
The period might be 12 months, two years or another timeframe considered appropriate by both sides and their legal advisers.
For many international purchasers, this should not be regarded as financial assistance.
They may already have substantial resources.
What they want is simply time.
When the right home appears before the timing is perfect
This may be one of the most natural situations in which a flexible purchase could work.
Imagine a couple from the Netherlands who know they want to spend much more time in Benahavís once they retire in two years.
They visit now and find exactly the right home.
The position is perfect. The terrace catches the afternoon sun. The community feels right. They can already picture themselves spending winters there and welcoming family during the summer.
The problem is not that they are uncertain about the Costa del Sol.
The property has simply appeared two years earlier than their plans.
Under a conventional sale, they face a difficult choice: buy immediately and restructure their finances sooner than intended, or walk away and hope something equally suitable appears later.
A properly structured rent-to-buy arrangement potentially creates another route.
They can agree the future purchase today, make a meaningful financial commitment and begin enjoying the home during the intervening period.
For the buyer, it brings their property purchase into line with their life plans.
For the seller, it creates a committed prospective purchaser and rental income during the agreed period.
That is a much more positive story than simply delaying a purchase because somebody is nervous about the market.
This should be more than “rent now and decide later”
For the seller, this distinction is crucial.
A carefully structured purchase option has genuine value.
If today’s €900,000 property is worth more in two years and the buyer retains the right to purchase at the previously agreed price, that buyer has benefited from having the price fixed.
The seller has surrendered some potential future upside in exchange.
It is therefore reasonable that the terms reflect the value of the flexibility being offered.
There could be a meaningful initial option payment. The rental level needs to make commercial sense. The parties should agree clearly whether any proportion of rent is deducted from the eventual purchase price, and what happens if the buyer chooses not to complete.
The arrangement should work for both sides rather than becoming a long rental period during which all of the commercial risk sits with the owner.
Flexibility can give buyers greater confidence
After several years of rising prices, it is natural for buyers to take a little more time over a major discretionary purchase.
That does not mean they believe the Costa del Sol has become less attractive.
Nor does it necessarily mean they expect values to fall.
It may simply reflect the fact that buying a €750,000, €1 million or €1.5 million second home is a larger capital decision today than it was a few years ago.
A rent-to-buy arrangement cannot remove market risk, and it should never be presented as doing so.
What it can do is change the timing of the buyer’s capital commitment.
For somebody who has found a particular home they genuinely want, being able to secure it today, spend time living in it and complete the purchase later may make the decision considerably easier.
If the future price is fixed, the buyer also gains clarity over what that eventual purchase will cost.
That certainty has value, and the commercial terms should reflect it.
And what does the seller gain?
The obvious compromise is that the seller does not receive the full purchase price immediately.
For an owner who needs the proceeds to fund their next home or another investment, that may make the idea unsuitable.
There are, however, many Costa del Sol owners who do not urgently need to release all of the capital from a second property.
For them, the calculation can be quite different.
The home may continue producing income during the option period. There may be an initial payment for granting the option, and the seller can preserve the agreed purchase value without immediately reducing the asking price simply to generate another round of interest.
Most importantly, the owner moves from having an unknown future purchaser to somebody who is already living in the property and has made a meaningful financial commitment towards acquiring it.
That emotional element should not be underestimated.
A buyer who has spent a year or two waking up in the home, entertaining friends on the terrace, getting to know the neighbourhood and imagining their future there is likely to feel very differently about completing the purchase from somebody viewing the property for forty-five minutes on a Tuesday afternoon.
Could flexibility preserve more value than a price reduction?
This may become particularly relevant in a market where buyers remain interested but take longer to commit.
Suppose a home has been marketed at €700,000 without attracting an acceptable offer.
Reducing it to €650,000 gives away €50,000 immediately if the lower price produces a sale.
A different option could be to retain the €700,000 purchase price while allowing a suitable buyer 18 or 24 months before completion.
During that time, the seller receives rent and may also receive a separate payment for granting the purchase option.
That arrangement will not automatically produce the better result. Every property and every seller is different.
But the numbers are worth comparing before assuming that a price reduction is the only answer.
Sometimes offering flexibility over how a property is bought may preserve more value than simply reducing what it costs.
Spanish residents face a different version of the same problem
The international second-home market is central to the Costa del Sol, but Spanish buyers should not be forgotten.
For them, rent-to-buy may solve a different problem altogether.
There are households with permanent employment, respectable salaries and the ability to comfortably support the monthly cost of home ownership who still struggle to accumulate the large cash deposit required to purchase while simultaneously paying today’s rents.
They can afford the home once they are in it.
The difficulty is reaching the starting line.
For these buyers, a carefully structured rent-to-buy agreement can provide a bridge from tenancy to ownership, particularly where part of the agreed payments contributes towards the eventual purchase.
The motivation is quite different from that of the international purchaser who simply wishes to delay releasing investment capital, yet the underlying mechanism can potentially work for both.
The buyer still needs to be financially credible
Rent-to-buy should never be treated as a way of making an unaffordable property appear affordable.
The strongest arrangements are likely to involve buyers whose issue is timing rather than fundamental affordability.
They may be building additional savings, waiting for another home to sell, restructuring investments, approaching retirement or expecting their residency or employment circumstances to change.
If a mortgage will ultimately be required, however, the likely financing position should be considered at the beginning rather than at the end.
Neither buyer nor seller benefits from spending two years working towards a purchase that was never realistically financeable.
A financially credible buyer with a clear route towards completion is therefore very different from somebody simply hoping that their circumstances will improve.
Not every Costa del Sol property will suit the idea
There is no suggestion that rent-to-buy should replace the conventional sales process.
At the very highest end of the Benahavís luxury market, the circumstances can be completely different. Someone purchasing a multi-million-euro villa in a private estate may have little need for traditional financing, although even wealthy buyers can occasionally find deferred completion useful for investment, tax or timing reasons.
The concept becomes particularly interesting through the broad middle and upper-middle sections of the market: quality apartments, penthouses, townhouses and villas that appeal to international lifestyle buyers as well as people planning a permanent move to southern Spain.
It may also appeal to owners who simply have the flexibility to consider a different transaction structure rather than needing the entire sale proceeds immediately.
And importantly, an owner does not necessarily have to advertise a property as rent-to-buy from the outset.
Sometimes the possibility may arise simply because the right buyer asks the right question — and the seller is willing to listen.
The legal structure matters
Any arrangement of this kind needs to be approached carefully.
A rent-to-buy agreement creates meaningful rights and obligations for both sides. The purchase price, length of the option, rental terms, option payment, treatment of rental credits and consequences of either party failing to fulfil their obligations all need to be clear from the beginning.
Purchase options can, subject to the appropriate legal requirements, also be registered at Spain’s Property Registry.
For that reason, this is not something that should be improvised through a few additional clauses added to an ordinary rental agreement.
Both buyer and seller should receive appropriate independent Spanish legal and tax advice before entering into the arrangement, with the contract setting out clearly what happens if the purchase completes — and what happens if it does not.
Perhaps the opportunity is simply greater flexibility
The Costa del Sol has not lost its international audience.
Foreign purchasers continue to represent an unusually large part of Málaga province’s property market, and Marbella, Benahavís and Estepona remain among southern Europe’s most established lifestyle destinations.
What has changed is the size of the commitment.
After several years of strong price growth, buying a second or third home can mean releasing hundreds of thousands of euros in capital before the keys are handed over.
Some purchasers will do that without hesitation.
Others may prefer to keep investments in place a little longer, wait for another property to sell, align the purchase with retirement or simply find a structure that fits more comfortably around their existing plans.
They have not necessarily fallen out of love with the property.
They may just need another way to buy it.
A fourth option for Costa del Sol sellers
Property sellers have traditionally faced three fairly familiar choices.
Find a buyer at the current price, wait, or reduce the asking price.
Perhaps there is sometimes room for a fourth.
Keep the value — but become more flexible about how and when the buyer pays for it.
Rent-to-buy will never suit every property, every seller or every purchaser.
Nor should it.
But in a market where values remain strong, international interest remains high and some buyers would simply benefit from greater flexibility over timing, it deserves to become part of the conversation.
Sometimes the difference between a property remaining for sale and becoming somebody’s home may not be another €50,000 reduction.
It may simply be finding a structure that allows both sides to say yes.
Could a flexible purchase work for you?
At The Benahavís Collection, we are beginning to explore rent-to-buy and other flexible purchase arrangements with suitable property owners across Benahavís and the surrounding Costa del Sol.
If you are thinking of selling and would consider receiving part of the purchase price later, we would be happy to discuss whether this type of arrangement could make sense for your property.
Equally, if you are a financially established buyer who has found that the timing of a conventional purchase does not quite suit your plans, tell us what you are looking for. In some cases, we may be able to approach owners who have never previously considered a flexible sale.
Every arrangement would remain subject to agreement between buyer and seller and appropriate independent professional advice.
Sources & Further Reading
This article draws on recent Costa del Sol transaction data, foreign-buyer figures and developments within Spain’s second-home mortgage market.
Marbella Property Market
Recent transaction figures and the continued rise in Marbella residential property values.
International Buyers
Foreign buyer activity across Spain and the continuing importance of overseas purchasers in Málaga province.
Second-Home Mortgages
Why demand for second-home borrowing is not always translating into completed mortgages.
Important: This article is intended as general property-market commentary rather than legal, tax, mortgage or financial advice. Rent-to-buy, purchase-option and deferred-completion arrangements can have significant legal and tax consequences. Buyers and sellers should obtain appropriate independent professional advice before entering into any agreement.
Looking for a home outside Benahavís?
Holiday Homes Spain
covers the whole Costa del Sol.